Health Insurance 2027: What Changed and Who Still Qualifies
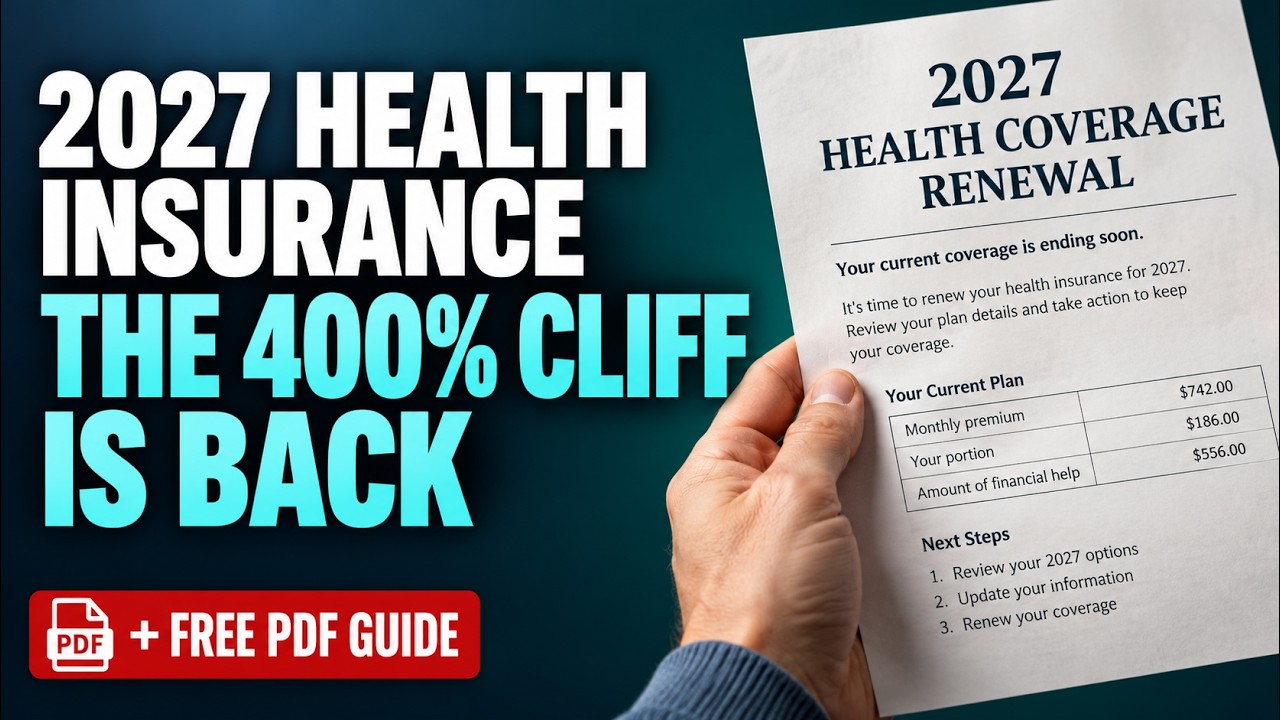
Sometime before November, two letters arrive. One comes from your health insurance company and one comes from the Marketplace. Between them they tell you what your plan costs next year and how much help you get paying for it. Millions of people never open either one, and their coverage renews on its own. That is the most expensive mistake you can make with health insurance in 2027.
Automatic renewal does one thing well. It keeps you covered. What it cannot do is know what you expect to earn next year, and for 2027 that number matters more than it has in years. Three things changed about the money. And one date is being widely misreported, so we cover the calendar too.
What actually changed for health insurance in 2027
From 2021 through the end of 2025, Congress made the premium tax credit more generous. Those enhancements were temporary. They expired on December 31, 2025, and they have not been renewed. What came back is the older, tighter structure, and it changed three things at once.
None of this came from your insurance company. The rules are federal. Your final price still moves with what insurers charge where you live, because the credit is measured against a benchmark silver plan in your own area.
The income ceiling is back
You can qualify for the premium tax credit with household income from 100 percent of the federal poverty level up to 400 percent. Above 400 percent, eligibility generally ends. It does not taper off. One dollar over the top of that range and the federal credit stops.
Eligibility for 2027 coverage is measured against the poverty guidelines published for 2026, because the Marketplace uses the figures in effect when open enrollment opens. These are the 2026 guidelines for the 48 contiguous states and the District of Columbia.
| Household size | 100% of poverty | 400% of poverty |
|---|---|---|
| 1 | $15,960 | $63,840 |
| 2 | $21,640 | $86,560 |
| 3 | $27,320 | $109,280 |
| 4 | $33,000 | $132,000 |
| 5 | $38,680 | $154,720 |
| 6 | $44,360 | $177,440 |
| 7 | $50,040 | $200,160 |
| 8 | $55,720 | $222,880 |
The help also got smaller below the line. For 2027, a household between 300 and 400 percent of poverty is expected to pay 10.22 percent of its income toward a benchmark plan before any credit applies. Plenty of people who still qualify will pay more than they paid last year. Eligible is not the same as affordable.
Which income figure the Marketplace uses
The number that decides your credit is not your salary. It is modified adjusted gross income, and it covers the whole household. Start with the adjusted gross income from your federal tax return, then add back tax exempt interest, the untaxed portion of Social Security benefits, and any foreign earned income you excluded.
The trap is money that never touches a paycheck. Selling stock, cashing out cryptocurrency, a taxable withdrawal from a retirement account, selling a second property. Any one of those can push a year over the line while your monthly pay never changes. If you are weighing when to start retirement income, our guide to SSDI and Social Security retirement covers how those choices land on the same tax return.
Household is a tax question, not a housing question. It is you, your spouse if you file jointly, and everyone you claim as a dependent. A roommate is not in your household. An adult child you still claim is, even if they live somewhere else. And if a dependent earns enough to be required to file their own federal return, their income goes into the household total.
Three ways to be disqualified regardless of income
Married filing separately
If you are married, you generally have to file a joint return to claim the premium tax credit at all. File separately and you are usually barred, whatever your income is. There are narrow exceptions for people living apart from a spouse because of domestic abuse or spousal abandonment. Outside those, a couple well under the ceiling can end up with nothing because of a filing decision made for another reason entirely.
An affordable offer of job based coverage
If you or your spouse can get employer coverage that the rules count as affordable and adequate, you generally cannot take a credit for a Marketplace plan instead. For 2027, an employer offer counts as affordable if the employee’s share of self only coverage is no more than 10.22 percent of household income. Ask for that number in writing before you shop.
Immigration status, changing January 1, 2027
From that date, the federal premium tax credit and income based help with deductibles are limited to lawful permanent residents, Cuban and Haitian entrants, and people lawfully present under a Compact of Free Association. Some lawfully present people who received this help before will not qualify from that date. They can still buy a Marketplace plan at full price.
The repayment cap is gone
Most people take the credit in advance. The Marketplace estimates your income, pays the money to your insurer every month, and you settle up when you file. There used to be a safety net under a bad guess: the amount you had to pay back was capped, and the cap was low for lower income households.
That cap was repealed for tax years beginning after December 31, 2025. There is no limit now, at any income level. Imagine a household of two that estimated $80,000 and took the credit all year. A bonus and some stock sales land in November, and the year finishes at $88,000. That is above $86,560, so the entire year of advance credit comes back with the tax return. Nothing is prorated.
There are two ways to protect yourself. Take less credit in advance than you qualify for and claim the rest as a refund when you file, which changes when you get the money rather than whether you get it. Or report income changes to the Marketplace during the year, as they happen, so the credit adjusts going forward.
The real deadlines
On healthcare.gov, open enrollment for 2027 coverage runs from November 1, 2026 to January 15, 2027. You may have read that it now ends on December 15. A 2025 federal rule was set to do that, but after a court case over that rule, the Centers for Medicare and Medicaid Services confirmed in July 2026 that the federal dates are unchanged.
December 15 is still the date that matters most. It is the last day to choose a plan that starts January 1. Choose between December 16 and January 15 and the plan starts February 1. If you have no other coverage, that is a month uninsured.
If your state runs its own Marketplace, check its dates. States set their own, and several run later than January 15: Covered California and NY State of Health run to January 31, 2027, and the Massachusetts Health Connector to January 23. If you are also making Medicare decisions this fall, those dates are different again, and we cover them in our guide to Medicare open enrollment for 2027.
After the deadline closes, getting in generally takes a qualifying life event: losing other coverage, marriage, a birth or adoption, a permanent move, or certain changes in income or household. Be ready to prove it with documents, and know that the monthly enrollment opportunity that once existed for very low income households is not available for 2027. Medicaid and the Children’s Health Insurance Program take applications all year, with no enrollment window at all.
What to do, in order
- Open both letters when they arrive, in late October.
- Estimate your 2027 household income, including anything you expect to sell or withdraw.
- Compare it to the ceiling for your household size.
- Log in and run your own application, even if you are keeping the same plan.
- Check the plan itself: are your doctors in network for 2027, and are your prescriptions on the formulary?
- If you qualify for extra savings, price the silver plans properly. Cost sharing reductions generally attach only to silver, so a silver plan can beat a cheaper bronze plan once the deductible is counted.
- Decide how much credit to take in advance.
- Enroll by December 15 for coverage from January 1 (January 15 is the last day to enroll at all), and pay the first premium. An enrollment without a payment is not coverage.
Being just over the ceiling is not always the end of it. A deductible contribution to a traditional individual retirement arrangement or a health savings account contribution both reduce modified adjusted gross income, and both can generally be made up to the April filing deadline and still count for the prior year. Anything that comes out of your paycheck, like a 401(k) or a workplace health savings account deduction, closes with the calendar year. Whether any of it applies to you is a conversation with a tax professional.
Download the free guide
Our free companion guide has the full income table by household size, a worksheet for estimating your 2027 income, the official phone numbers, and the lawful ways to bring that number back under the line. No email required.
More free guides on government programs, all without an email address, are on our free guides page.
Correction, October 14, 2026: an earlier version of this guide said federal open enrollment for 2027 ends December 15. It runs to January 15, 2027. December 15 is the last day to choose a plan that starts January 1.
GovClarity is an independent educational resource. This is not tax advice or insurance advice. For your own return, talk to a tax professional. For help choosing a plan, the free Marketplace assisters at localhelp.healthcare.gov cannot be paid by commission and cannot charge you.