Unlock Your VA Home Loan Benefits: Complete Guide for Veterans in 2025
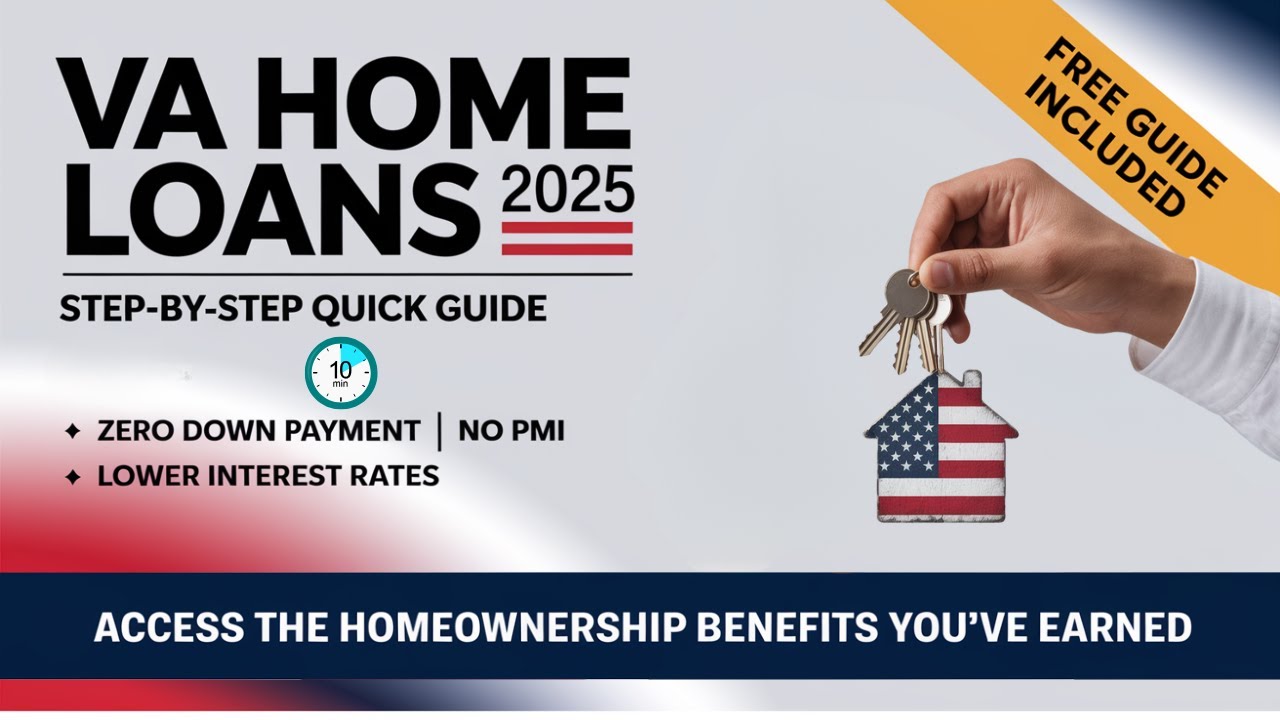
A VA home loan means no down payment up to your county limit, against 5% to 20% on a conventional loan. On a $350,000 home that is roughly $70,000 you do not have to find. There is no private mortgage insurance, ever, which saves $1,200 to $3,600 a year until you would have reached 20% equity. And if you receive VA disability compensation, the funding fee is waived entirely.
Watch this step-by-step GovClarity video guide. Subscribe to our YouTube channel for new guides every week.
Information sourced as of January 2025. County loan limits, funding fees and the rate examples below match our companion PDF using 2025 figures. Loan limits and fees change annually, so check VA.gov for current numbers before you apply.
What this benefit is actually worth
No down payment up to your county limit, against 5% to 20% on a conventional loan. On a $350,000 home that is roughly $70,000 you do not have to find.
No private mortgage insurance, ever, regardless of how little you put down. That alone saves $1,200 to $3,600 a year until you would have reached 20% equity.
And if you receive VA disability compensation, the funding fee is waived entirely.
How a VA home loan works
The Department of Veterans Affairs does not lend you money. It guarantees a portion of the loan against default, which lowers the lender’s risk and lets approved lenders offer terms they otherwise could not. The programme dates to 1944 and the original GI Bill, and has helped around 25 million veterans become homeowners.
The advantages, in numbers
| Cost | VA loan | Conventional loan |
|---|---|---|
| Down payment | $0 up to the county limit | 3% to 20% of the purchase price |
| Mortgage insurance | None | $100 to $300 a month with under 20% down |
| Interest rate | Typically 0.25% to 0.5% lower | Market rate |
| Funding fee | 2.3% first use, and it can be financed | Not applicable |
| Closing costs | Limited by VA rules | No caps |
| Monthly payment on $350,000 | About $2,100 | About $2,350 |
Those payment figures assume 6% on the VA loan and 6.5% conventional with 5% down, including taxes and insurance on a 30 year fixed term at 2025 rates. The difference works out around $250 a month, or roughly $90,000 across a 30 year term.
Other advantages worth knowing: no prepayment penalties, sellers can contribute up to 4% toward closing costs and concessions, and the VA provides foreclosure avoidance assistance including loan modifications if you hit financial hardship.
The funding fee
This is the one extra cost, at 2.3% for first time use and 3.6% for subsequent use as of 2025. It can be financed into the loan rather than paid upfront, and it is waived completely for veterans receiving VA disability compensation.
Loan limits and entitlement
The county loan limit for most areas in 2025 was $766,550. You can buy up to that with nothing down, and above it with a down payment of 25% of the excess.
Your entitlement is what the VA guarantees. Basic entitlement is $36,000, with bonus entitlement of up to $131,400 depending on county limits.
Restoring entitlement, because this benefit is reusable
You can use a VA loan more than once across your lifetime, but entitlement has to be restored first to use it in full. There are four routes:
- Sell the property and pay off the loan in full. The most common route.
- Have another qualified veteran assume the loan, substituting their entitlement for yours.
- Repay the loan in full but keep the property. This is a one time only option.
- Use a one time restoration if you paid off a previous VA loan but still own the home.
Submit VA Form 26-1880, Request for Certificate of Eligibility, with evidence the prior loan is paid and, where relevant, that you disposed of the property. Veterans with partial entitlement can still buy, though a down payment may be needed.
Do you qualify?
| Service | Minimum requirement |
|---|---|
| Active duty during wartime | 90 continuous days |
| Active duty during peacetime | 181 continuous days |
| National Guard or Reserves | 6 years, or 90 days active duty during a national emergency |
| Currently active duty | 90 continuous days |
Wartime periods are World War II from September 16, 1940 to July 25, 1947; Korea from June 27, 1950 to January 31, 1955; Vietnam from August 5, 1964 to May 7, 1975, or from February 28, 1961 for those who served in Vietnam; and the Persian Gulf War from August 2, 1990 to the present, which includes Operations Enduring Freedom, Iraqi Freedom, New Dawn, Inherent Resolve and Freedom’s Sentinel.
Surviving spouses
You may qualify as the unmarried surviving spouse of a veteran who died in service or from a service connected disability, the surviving spouse of a veteran who was totally disabled and then died even if not service connected, or the spouse of a service member missing in action or a prisoner of war.
Discharge status
Honorable and General under honorable conditions are fully eligible. Other Than Honorable may still qualify after a Character of Discharge review, which is worth requesting rather than assuming you are excluded. Bad Conduct by general court martial is generally not eligible, and Dishonorable is not.
Debt to income, and what lenders actually look at
The VA sets no specific limit, but most lenders want a debt to income ratio below 41%. Exceptions up to 50% or higher are made with compensating factors.
Front end is the share of income going to housing costs. Back end is everything, including car loans, student loans and credit cards. If your gross monthly income is $6,000 and total monthly debts including the new mortgage are $2,400, your ratio is 40%.
Compensating factors that can get a higher ratio approved: a credit score of 680 or above, substantial cash reserves after closing, minimal obligations beyond the mortgage, a proven record of paying housing costs equal to or above the proposed payment, and residual income above VA requirements.
Refinancing with the streamline option
If you already hold a VA loan, the Interest Rate Reduction Refinance Loan, known as the IRRRL or VA Streamline Refinance, lets you lower your rate or move from an adjustable to a fixed rate with minimal paperwork. In most cases no new appraisal is required.
Timeline
Expect 30 to 45 days from pre-approval to closing on average. Start by requesting your Certificate of Eligibility, which you can do through VA.gov, your lender, or by submitting Form 26-1880.
For the wider picture of what you have earned, see our complete VA benefits guide and our VA healthcare guide.
📥 Free PDF Guide
Download our free step-by-step guide for this topic. No email required.
Browse all our guides on the Free Guides page.
Frequently asked questions
Do I really need no down payment?
Correct, up to your county loan limit, which was $766,550 in most areas for 2025. Above that you put down 25% of the amount exceeding the limit.
What is the funding fee and can I avoid it?
2.3% for first time use, 3.6% thereafter. It can be financed into the loan, and it is waived entirely for veterans receiving VA disability compensation.
Can I use a VA loan more than once?
Yes. The benefit is reusable for life, but you generally need to restore your entitlement first, usually by selling the property and paying off the loan.
What credit score do I need?
The VA sets no minimum. Lenders set their own, and 680 or above helps considerably if your debt to income ratio is high.
Can surviving spouses use this?
Yes, in several circumstances, including unmarried surviving spouses of veterans who died in service or from a service connected disability.
How long does it take?
Typically 30 to 45 days from pre-approval to closing.
Is there a penalty for paying it off early?
No. VA loans carry no prepayment penalties, so extra payments build equity faster with no downside.
Related GovClarity guides
Official resources
- VA home loan information and Certificate of Eligibility: VA.gov/housing-assistance/home-loans
- VA benefits helpline: 1-800-827-1000
- Form 26-1880: available through VA.gov
- Current county loan limits: VA.gov
Details as of January 2025. Loan limits, funding fees and rates change, so verify at VA.gov before applying. GovClarity is not a government agency, is not a lender, and does not provide financial advice.